Fluor-JGC Lands $15B LNG Canada Phase 2 Deal: What Subs Can Expect
Fluor and JGC have locked in the prime contractor seat on LNG Canada’s Phase 2, and the split of that work will shape who gets field hours at Kitimat, British Columbia, Construction Dive reports. The 50/50 joint venture will deliver engineering, procurement, fabrication, construction and commissioning for two new liquefaction trains and an additional LNG storage tank. Each partner is booking $7.5 billion, for $15 billion combined.
The award is firm. The source does not say how the work will be divided among self-perform crews and subcontractors, and it names no bid dates or bidder lists. Everything below on likely packages is analysis, not confirmed scope.
Background
According to Fluor’s news release, as cited by Construction Dive, the Irving, Texas-based contractor will book its $7.5 billion share in the third quarter of fiscal 2026. Yokohama-based JGC separately announced the same $7.5 billion figure for its share. The Canadian government estimates Phase 2 will need about $23 billion overall, per Briefs Finance. The source does not explain the gap between that estimate and the $15 billion JV contract.
The expansion will double the facility’s production capacity to about 28 million tonnes per annum. LNG Canada is owned by Shell, Petronas, PetroChina, Mitsubishi Corp. and Korea Gas Corp. Shell expects commercial operations to begin in the early 2030s.
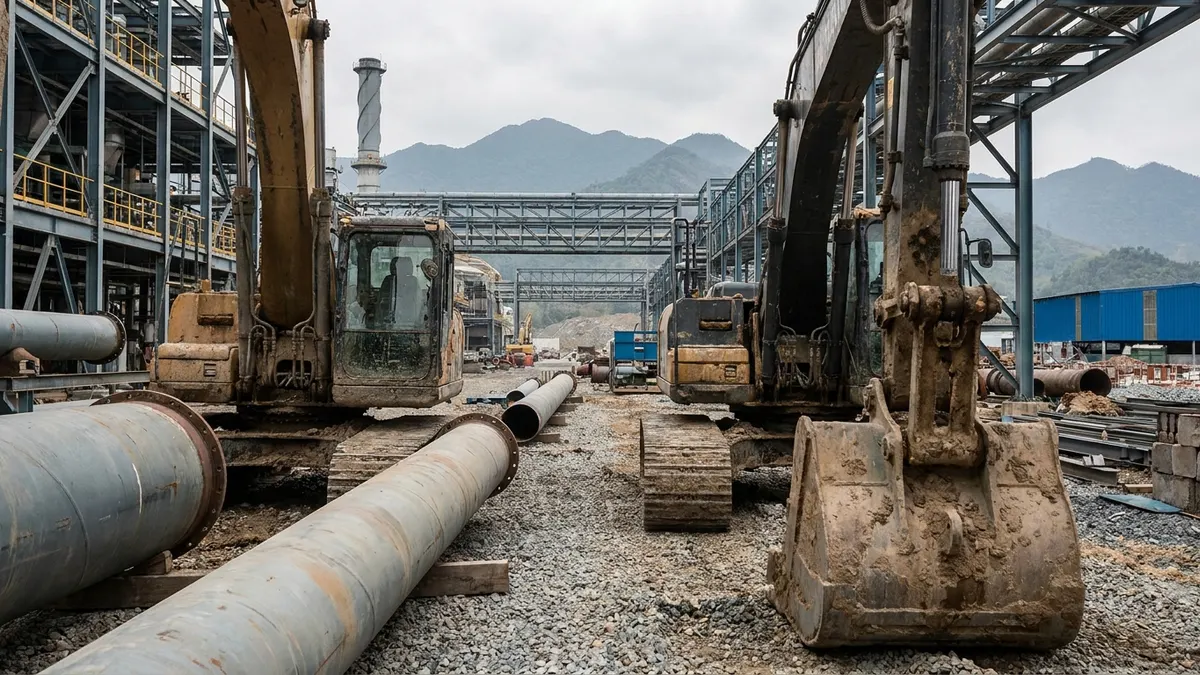
Fluor and JGC also delivered Phase 1. LNG production began in June 2025, and the contractors completed the facility handover in October 2025. Phase 1 relied on modular construction: 215 modules were fabricated overseas and shipped to Kitimat, and the final module arrived from China in July 2023.
Analysis
The same team is back, which favors continuity in procurement. Owners and EPC contractors that have just completed a facility together rarely rebuild their supply chain from scratch. The JV has a recent, finished project at the same site. It is reasonable to expect it to lean on vendors and subcontractors that performed in Phase 1. That is an inference, and the source does not say it. But it means newcomers face a harder first conversation than proven Phase 1 performers do.
Modular precedent points to where the field work sits. The source confirms Phase 1 used 215 overseas-fabricated modules. It does not say Phase 2 will repeat that approach. If it does, the largest share of fabrication hours would again sit outside Western Canada. The local field scope would then center on what happens after modules land: setting and aligning, interconnecting piping, electrical and instrumentation tie-ins, civil and foundation work, and commissioning support. If the JV shifts more work to on-site stick-build, the mix changes. That is the single biggest unknown for Western Canadian and US subs, and the JV has not addressed it in the source.
Packages likely to matter, stated as inference. Based on the confirmed scope of two trains plus a storage tank, the work implies civil and foundation packages, tank construction, process and utility piping, electrical and instrumentation, mechanical installation, and commissioning. Temporary facilities and workforce housing would also be needed for a build of this size. None of these packages appears in the source as awarded, tendered or self-performed. Treat this as a scoping checklist, not a bid calendar.
Timeline clarity is thin. The source gives one date anchor for the back end: Shell’s early 2030s commercial operations expectation. It gives no construction start, no mobilization window and no subcontract release schedule. Subs should not assume bid packages are imminent. After an EPC award, early work typically runs through engineering and procurement before field packages firm up. That is general industry reasoning, not something stated by Fluor or JGC.
The $15 billion versus $23 billion gap matters for scoping. The JV’s $15 billion covers its EPC role. The government estimate for the full phase is higher, but the source does not say what sits outside the EPC contract. Subs should not size their opportunity against the $23 billion headline. Only the $15 billion is tied to the Fluor-JGC scope.
A two-headed JV complicates access. Fluor and JGC each hold 50% and each announced $7.5 billion. The source does not say how they will split procurement, which means a sub may need to ask which partner leads a given discipline. Outreach to only one partner could miss the right buyer.
What It Means for Subcontractors
- Ask both partners directly about the bidder list. The source does not describe any vendor registration or prequalification process. Contact Fluor’s and JGC’s project procurement teams for LNG Canada Phase 2 and confirm in writing which partner manages each discipline you work in.
- Document your Phase 1 record. The JV just finished a Kitimat project, with handover in October 2025. If you worked at the site, assemble safety statistics, schedule performance and headcount history by trade. Those will matter most to a team rehiring from a known pool.
- Price for module hookup, not just stick-build. Phase 1 used 215 overseas modules. Until the JV confirms Phase 2 methods, build estimates for both scenarios. Cover piping tie-ins, E&I terminations and mechanical alignment for modular work, and full field installation if scope shifts on-site.
- Civil, tank and foundation contractors should confirm sequencing. Two new trains and a storage tank imply early-stage site and foundation work. The source gives no dates, so ask the JV when civil packages are expected to be released rather than assuming a window.
- Commissioning specialists should get on the radar early. The JV’s scope explicitly includes commissioning. Confirm whether commissioning support will be self-performed or subcontracted, and who owns that decision.
- US-based subs should size their Canadian entry costs. The source says nothing on cross-border labor or work-authorization requirements, so confirm those with the JV before committing crews.
- Plan capacity around a long horizon. With commercial operations expected in the early 2030s per Shell, the build spans multiple years. Avoid committing crews against specific start dates until the JV publishes a mobilization schedule.